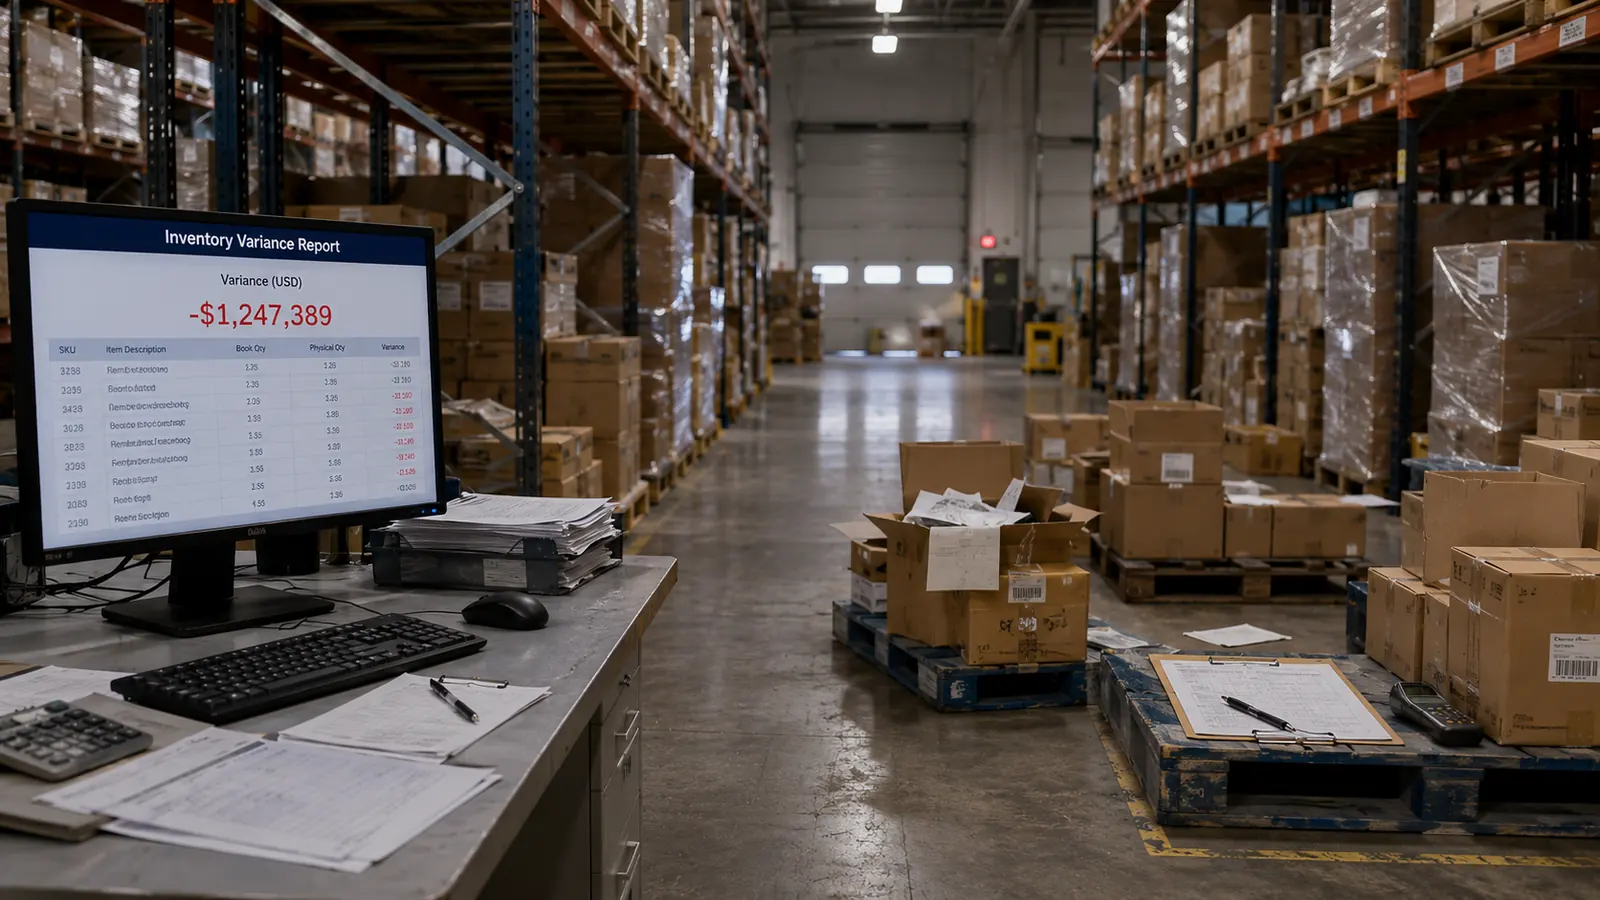
The calculation can be correct while the decision is wrong.
An estimate uses an approved labor rate, an established material standard, and a familiar routing. The spreadsheet adds everything perfectly. The quoted margin looks reasonable.
Then the job reaches the floor, and the business discovers that the assumptions belong to a different operating reality.
Before applying AI to pricing or profitability analysis, the CFO and operations leader need to know whether the costs being used still describe how the work gets done.
Find out what the standard assumes
A standard cost is a maintained assumption about the resources needed to perform work. It can become stale quietly.
Material pricing changes. Crew composition changes. A new product mix creates more setups. Maintenance problems slow a machine. Scrap moves. Freight arrangements change. Supervision that used to cover several jobs is now concentrated on one.
An AI system cannot determine that an approved cost is current simply because it came from the ERP. If the source is outdated, a more sophisticated analysis can still produce a misleading answer.
Start with a product family or recurring job type where quoted results and actual performance disagree. Avoid trying to recalibrate the entire business at once.
Separate bad assumptions from bad execution
The controller should lead the comparison with operations. Review the original estimate, the version of the cost standard used, recorded material consumption, labor hours, setup time, scrap, and approved scope changes.
Do not automatically replace a standard with the latest actual result. An unusual breakdown, incomplete labor reporting, an engineering change, or an incorrectly coded transaction can make that result a poor baseline.
The useful question is why the difference occurred. Was the expected production rate unrealistic? Did the work run on a different machine? Was additional scope never added to the estimate? Did actual hours land on the wrong job?
Those causes require different corrections. Averaging them together may hide the problem the business needs to solve.
Maintain the cost foundation deliberately
Data Curation & Governance should establish a source and owner for material prices, labor assumptions, routings, units of measure, and effective dates. Keep a record of what changed and why. Preserve the assumptions used for a quote so a later review can reconstruct the decision.
Workflow Optimization should define how purchasing, operations, estimating, and finance propose and approve changes. Make sure an updated assumption reaches the people preparing new quotes. Agree on how exceptions are handled and when a change triggers a pricing review.
The controller owns the integrity of the management cost model. Operations owns validation of production assumptions. Purchasing owns the supporting supplier information. Changes to financial reporting or inventory accounting should follow the company’s established accounting review process.
Use AI to direct attention, not approve prices
AI can assist with summarizing variance explanations, identifying records that need investigation, or assembling supporting documents. Calculations should use controlled inputs and reproducible methods. A business owner should approve changes to standards and customer pricing.
The first production use should have a defined review queue and a clear rule for unresolved discrepancies. Do not let a generated explanation close a variance without evidence.
Within 30 days, have the controller and operations leader reconcile a representative set of completed jobs from one family. Produce a short list of corrected assumptions, data defects, and execution problems, with an owner and due date for each.
Track unexplained variance, estimate-to-actual differences, review effort, and the effect on new quoting decisions. The business objective is stronger margin visibility and lower pricing risk. Fund any AI layer only after its expected reduction in review effort or missed issues is weighed against its full cost.
A clean dashboard does not make a weak cost model dependable. The number becomes useful when someone can explain what it assumes and show that the assumption still holds.
Related perspective: Master Data Is the Bottleneck Nobody Wants to Own